MIAMI — PROFILEmiami’s third annual Pre-Construction Development Summit brought more than 450 South Florida real estate professionals to the Coral Gables Museum on Oct. 9, where developers, brokers, financiers and sales executives gathered to compare notes on demand, capital, construction risk and the design trends shaping the next wave of projects across the region.
The summit combined a development showcase, three panel discussions and an evening networking reception in downtown Coral Gables. The format was built to connect active projects with the people who market, finance and buy them, while also offering a snapshot of the South Florida pipeline from Miami to Fort Lauderdale and the Palm Beaches.
The event was presented by Sterling Risk Insurance and held at a venue that fit the subject matter closely: a museum focused on architecture, urban planning, preservation and design. A portion of ticket proceeds benefited the Coral Gables Museum.
| Project Detail | Information |
|---|---|
| Event | 3rd Annual PROFILEmiami Pre-Construction Development Summit |
| Presented by | Sterling Risk Insurance |
| Date | Oct. 9, 2026 |
| Location | Coral Gables Museum, Coral Gables |
| Attendance | More than 450 members of South Florida’s development community |
| Format | Development showcase, three panel discussions and networking reception |
Showcase highlighted 24 projects across South Florida
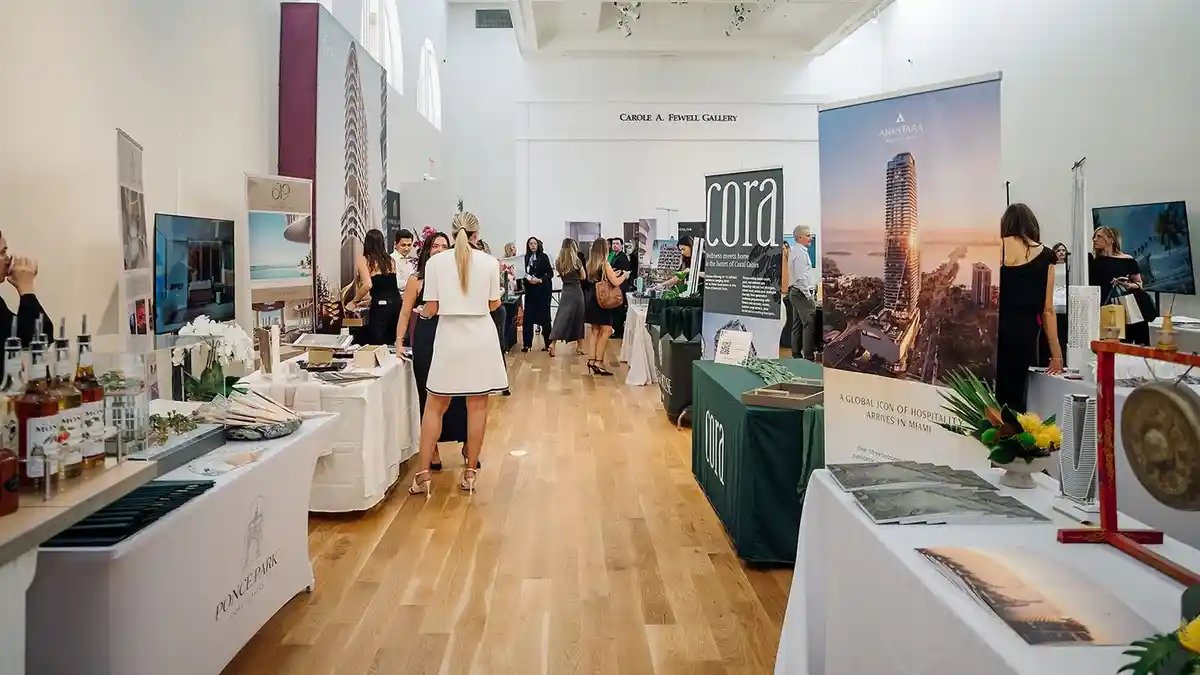
The summit’s centerpiece was a development showcase that brought together 24 projects and their sales teams under one roof. The lineup spanned several submarkets and product types, reflecting the range of buildings currently vying for broker attention in South Florida’s pre-construction landscape.
In Coral Gables and Coconut Grove, the participating projects included Ponce Park Residences Coral Gables and Ziggurat Coconut Grove from Allen Morris Company; Cassia The Residences at Coral Gables from Alta Developers; Cora Merrick Park from Constellation Group and The Boschetti Group; The Lincoln Coconut Grove from Element Development and LORE Development Group, in partnership with Leste Group and Opportunity Fundo de Investimento Imobiliário; and Colette Residences from Meta Development.
The showcase also featured a number of higher-profile Miami projects, including 619 Brickell by Nobu · Foster + Partners from 13th Floor Investments and Key International; Anantara Miami Resort & Residences from One Thousand Group; Edge House Miami from Grupo T&C; Elle Residences from Vertical Developments; HQ Residences Miami from Constellation Group, The Boschetti Group and Black Salmon; Season One Brickell from BI Group; and The William from Blue Road and Ilia Development.
Continuum Company presented three projects: Continuum 12000 Sport & Wellness Residences, Continuum Club & Residences and La Baia North. Other projects in the room included Ella Miami Beach from Constellation Group, Vietmar and The Boschetti Group, and Palma Del Lago Miami Lakes from GT Group USA.
Beyond Miami-Dade County, the summit also featured Fort Lauderdale’s Pier Sixty-Six Residences from Tavistock and Selva House from OUTTELIER. In Palm Beach County, the projects on display included Related Ross’ Shorecrest WPB, Edgeworth West Palm Beach and South Flagler House, as well as Greenview at Presidential from Lennar and BH Group.
For brokers and developers, that mix matters. The event was structured less like a trade expo and more like a compressed market survey, creating a setting where teams could compare product positioning, buyer profiles and sales strategies while moving from one project table to another.
Panelists focused on demand, capital and the next cycle
The summit’s panel programming was organized around three questions that continue to define South Florida’s pre-construction market: where demand is headed, what it takes to get projects built and how developers are differentiating new product in a crowded pipeline.
The first panel, The South Florida Development Market: Demand, Markets, Development Sales & Navigating the Next Cycle, included Phil Gutman of Gutman Development Marketing, Fernando de Nunez y Lugones of Vertical Developments, Adam McPherson of Related Ross, Alisa Fiorini of GT USA and Ana Bozovic of Analytics Miami. Katya Demina of the Eklund | Gomes Team at Douglas Elliman Development Marketing moderated the discussion.
McPherson discussed West Palm Beach’s evolution and Related Ross’ role in shaping that market, while Bozovic brought a data-driven perspective to the conversation. The panel paired sales and development viewpoints with market analysis, offering a practical view of how sponsors are assessing demand as South Florida moves through yet another shifting cycle.
The second session, The Development Equation: Capital, Construction, Risk & What It Takes to Get Built, brought together Carlos Rosso of Rosso Development, Ian Bruce Eichner of Continuum Company, Alex Peters of Constellation Group and Olzhas Ayazbayev of BI Group. Jonathan Friedman of Sterling Risk Insurance moderated the panel.
That discussion centered on the fundamentals behind delivery: neighborhood selection, construction feasibility, risk management and the market’s appetite for different price points. Eichner and Rosso said buyers are increasingly drawn to places that offer safety, walkability and access to the water. They also addressed the need for more attainable product, noting that development does not have to be limited to multimillion-dollar homes.
The final panel, Developing with Differentiation: Branding, Design, Amenities & the Next Generation of South Florida Living, featured Allie Eichner of Continuum Company, Spencer Morris of Allen Morris Co., Jay Roberts of Prosper Group, Louis Birdman of One Thousand Group, Inigo Ardid of Key International and Fred Zutel of Lockton Insurance.
Morris emphasized provenance, design discipline and the growing sophistication of buyers, who now examine a project beyond its initial renderings and sales gallery. He said buyers are looking more closely at how a building will function in daily life, the quality of finishes and whether a residence can be customized to fit how they want to live. He also noted that some buyers are combining units, a sign of demand for larger and more tailored homes.
Roberts spoke about the newly revealed Bugatti Residences, while Birdman addressed standout amenities such as helipads and the role of architecture in giving a building a distinct identity. Ardid discussed the value branding can add, while also cautioning that a brand alone does not determine a project’s success.
Across the three conversations, participants returned repeatedly to wellness and longevity as central considerations for the next round of South Florida projects. That theme reflected a broader market shift: buyers are not just purchasing square footage, but evaluating how a building supports lifestyle, function and long-term livability.
What the summit says about South Florida’s pipeline
The summit offered a compact view of a market that has matured significantly over the past several years. South Florida remains one of the country’s most active regions for pre-construction condominium sales, but the conversation has broadened from simple demand toward a more detailed discussion of who is buying, what they want and how projects are being financed and delivered.
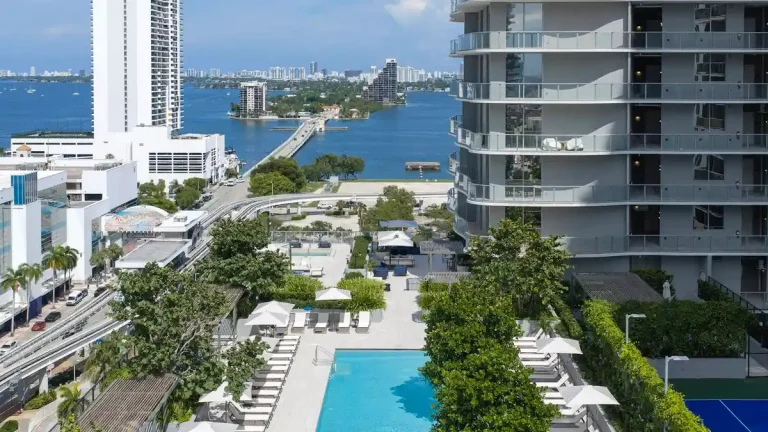
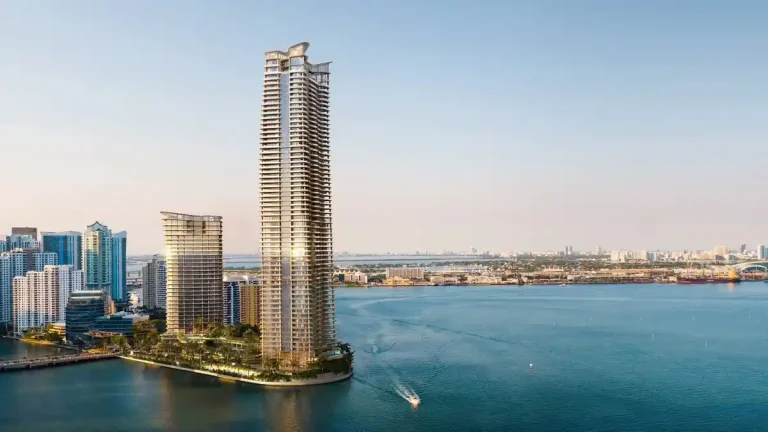
That evolution was evident in the projects showcased at the museum. The lineup included branded residences, boutique developments, waterfront towers and neighborhood-driven projects, underscoring the diversity of the current pipeline. It also showed how developers are working to distinguish products in submarkets that are increasingly competitive, especially in Miami, Coconut Grove, Coral Gables, Fort Lauderdale and West Palm Beach.
The inclusion of multiple companies with active portfolios in different counties also reflected the regional nature of the market. Buyers and brokers operating in South Florida often compare projects across city lines, and developers are now competing not only within a neighborhood, but also against other luxury and upper-market projects in neighboring cities.
That competitive pressure was part of the point of the summit. By placing 24 projects in one setting, PROFILEmiami created a forum where sponsors could explain positioning, brokers could compare offerings and lenders, insurers and consultants could hear firsthand how each project is being framed in the market.
Coral Gables provided an appropriate setting
Coral Gables has long been associated with architecture, planning and preservation, making the Coral Gables Museum a fitting venue for a summit focused on development. The location also placed the event within one of Miami-Dade County’s most established residential markets, where a mix of historic neighborhoods and newer luxury product continues to attract buyers.
The museum’s role in the event was not limited to its setting. The summit also included a charitable component, with a portion of ticket proceeds directed to the institution. That detail reinforced the event’s connection to the local civic and cultural landscape, not just the development industry.
PROFILEmiami said next year’s summit is planned for 2027. More information is available through the event’s website, realestatedevelopmentsummit.com.
Why the event matters for readers tracking South Florida real estate
While the summit itself did not announce a single new tower or groundbreaking, it offered an unusually broad look at the projects, executives and ideas currently driving South Florida pre-construction sales. For readers following the market, that kind of gathering is useful because it reveals not only what is being built, but how developers are positioning product in response to demand, financing conditions and buyer expectations.
The event also highlighted a recurring theme in the region: South Florida’s new development market is no longer defined only by ultra-luxury towers. Panelists repeatedly returned to the need for more balanced product, better urban design and residences that serve a broader range of buyers. At the same time, the showcase made clear that branded and high-amenity projects remain a major part of the pipeline, particularly in waterfront and transit-oriented locations.
For developers, brokers and consultants, the summit served as both a networking platform and a status check on the market. For observers of Miami and South Florida real estate, it was another sign that the region’s pre-construction sector remains active, competitive and increasingly segmented by neighborhood, lifestyle and price point.